


If you want to pass Financial-Accounting-Reporting real exam, selecting the appropriate training tools is necessary. And the Financial-Accounting-Reporting real questions from our Real4Prep are very important part. Real4Prep can provide valid Financial-Accounting-Reporting exam materials to help you pass Financial-Accounting-Reporting exam. The IT experts in Real4Prep are experienced and professional. Their research materials are very similar with the real exam questions.

The updated Admission Test Financial-Accounting-Reporting study materials and exam dumps of Real4Prep are composed by professionals and IT specialists; our Real4Prep provides a remarkable experience to anyone who are preparing for Financial-Accounting-Reporting exam. Our Real4Prep site is one of the best exam questions providers of Financial-Accounting-Reporting exam in IT industry which guarantees your success in your Financial-Accounting-Reporting real exam for your first attempt. The authority and reliability of our dumps have been recognized by those who have cleared the Financial-Accounting-Reporting exam with our latest Financial-Accounting-Reporting practice questions and dumps.
The Financial-Accounting-Reporting practice questions from our Real4Prep come along with correct answers and detailed answer explanations and analysis created for any level of experience of Real4Prep Financial-Accounting-Reporting exam questions. You can try our free demo questions of Financial-Accounting-Reporting to test your knowledge. Just try out our Financial-Accounting-Reporting free exam demo, you will be not disappointed. You will be happy to use our Admission Test Financial-Accounting-Reporting dumps.
Once you purchase Financial-Accounting-Reporting real dumps on our Real4Prep, you will be granted access to all the updates available of Financial-Accounting-Reporting test answers on our website in one year. Our testing engine version of Financial-Accounting-Reporting test answers is user-friendly, easy to install and upon comprehension of your practice tests, so that it will be a data to calculate your final score which you can use as reference for the real exam of Financial-Accounting-Reporting.
Unlike other providers on other websites, we have a 24/7 Customer Service assisting you with any problem you may encounter regarding Financial-Accounting-Reporting real dumps. Our Live Support team offers you a 10%+ Discount code that you can use when you decide to buy Admission Test Financial-Accounting-Reporting real dumps on our site. If you don't pass the exam for your first attempt with our dump, you can get your money back. So you have nothing to worry and have no lost.
After purchase, Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
Admission Test Financial-Accounting-Reporting Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Financial Reporting | 30-40% | - Special Purpose Frameworks - General Purpose Financial Statements - Financial Reporting for Nonprofits - State and Local Government Reporting - Conceptual Framework and Standard-Setting |
| Topic 2: Select Transactions | 25-35% | - Derivatives and Hedge Accounting - Leases - Subsequent Events and Fair Value Disclosures - Business Combinations and Consolidations - Fair Value Measurements |
| Topic 3: Select Financial Statement Accounts | 30-40% | - Assets - Liabilities - Equity - Expenses and Other Items - Revenue Recognition |
Admission Test Certified Public Accountant (Financial Accounting & Reporting) Sample Questions:
How should the effect of a change in accounting estimate be accounted for?
- A. By restating amounts reported in financial statements of prior periods.
- B. By reporting pro forma amounts for prior periods.
- C. In the period of change and future periods if the change affects both.
- D. As a prior period adjustment to beginning retained earnings.
Correct Answer: C 🗳️
In April 30, 20X4, Deer Corp. approved a plan to dispose of a component of its business. For the period January 1 through April 30, 20X4, the component had revenues of $500,000 and expenses of $800,000.
The assets of the component were sold on October 15, 20X4 at a loss. In its income statement for the year ended December 31, 20X4, how should Deer report the component's operations from January 1 to April 30, 20X4?
- A. $300,000 should be reported as an extraordinary loss.
- B. $500,000 and $800,000 should be included with revenues and expenses, respectively, as part of continuing operations.
- C. $300,000 should be reported as part of the loss on disposal of a component and included as part of continuing operations.
- D. $300,000 should be reported as a loss from operations of a component and included in loss from discontinued operations.
Correct Answer: D 🗳️
Coffey Corp.'s trial balance of Income Statement Accounts for the year ended December 31, 1988 as follows: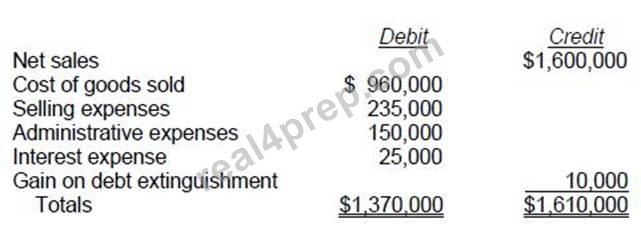
Coffey's income tax rate is 30%. The gain on debt extinguishment is considered a usual and recurring part of Coffey's operations. Coffey prepares a multiple-step income statement for 1988.
Income from operations before income tax is:
- A. $230,000
- B. $240,000
- C. $200,000
- D. $190,000
Correct Answer: B 🗳️
Which of the following is correct concerning financial statement disclosure of accounting policies?
- A. Disclosures should duplicate details disclosed elsewhere in the financial statements.
- B. Disclosures should be limited to principles and methods peculiar to the industry in which the company operates.
- C. Disclosure of accounting policies is an integral part of the financial statements.
- D. The format and location of accounting policy disclosures are fixed by generally accepted accounting principles.
Correct Answer: C 🗳️
On December 2, 20X1, Flint Corp.'s board of directors voted to discontinue operations of its frozen food division and to sell the division's assets on the open market as soon as possible. The division reported net operating losses of $20,000 in December and $30,000 in January. On February 26, 20X2, sale of the division's assets resulted in a gain of $90,000. Assuming that the frozen foods division qualifies as a component of the business and ignoring income taxes, what amount of gain/loss from discontinued operations should Flint recognize in its income statement for 20X2?
- A. $60,000
- B. $0
- C. $40,000
- D. $90,000
Correct Answer: A 🗳️


